Key takeaways
- "How much corpus do I need" depends entirely on your withdrawal rate — the same ₹50,000/month can need a very different corpus depending on what return you assume
- A quick sanity check: divide your desired annual income by 4% (the widely-cited "safe withdrawal rate") to get a conservative corpus estimate — then verify it properly with a real calculation
- A corpus that "lasts on paper" at a given return can still deplete faster than expected if actual returns fall short in the early years
- Inflation quietly increases the corpus you actually need — a flat ₹50,000/month buys less every year, even if the number never changes
- There's a real difference between a corpus that lasts a fixed number of years and one that lasts indefinitely (sustaining itself on growth alone)
Quick answer
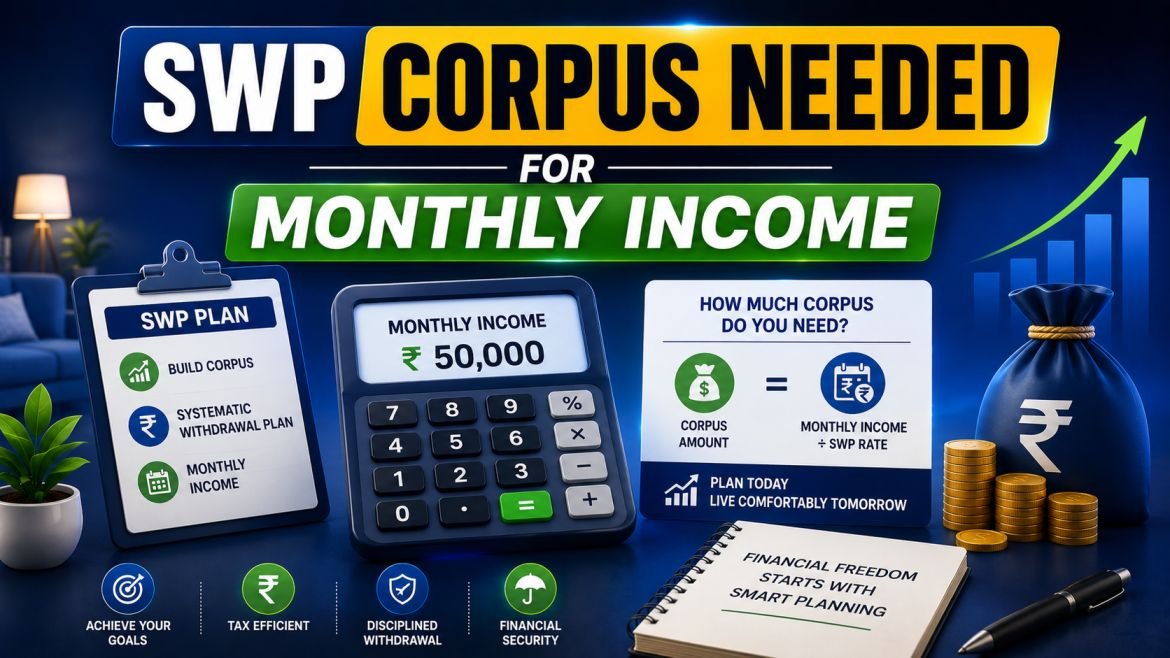
There's no single number — the corpus you need for ₹50,000/month depends on your assumed return, how long you need the income to last, and whether you want the corpus to deplete to zero or sustain itself indefinitely. As a rough starting point, the widely-cited 4% safe withdrawal rate suggests a corpus of about ₹1.5 crore for ₹50,000/month indefinitely — but this is a sanity check, not a precise answer for your situation.
A real example: Kavita works backwards from her target income
Kavita is planning her retirement and has a clear number in mind: she wants ₹50,000 a month to cover her expenses. What she doesn't know yet is how large a corpus that actually requires — and like most people approaching this for the first time, her first instinct is to guess a round number rather than work it out properly.
The fast way to estimate: the 4% rule, in reverse
The quickest sanity check uses the same 4% safe withdrawal rate benchmark used in FIRE (Financial Independence, Retire Early) planning, just worked backwards:
Annual income needed = ₹50,000 × 12 = ₹6,00,000
Corpus estimate (4% rule) = ₹6,00,000 ÷ 4% = ₹1,50,00,000 (₹1.5 crore)
This is a conservative estimate meant to sustain the corpus indefinitely (with annual inflation adjustments), based on historical backtesting from US market data over a 30-year horizon — not a guarantee, and not specific to Indian markets, taxation, or a different withdrawal duration.
Common mistake: treating the 4% rule as a precise formula rather than a rough starting reference. It was derived from a specific historical dataset and a 30-year horizon — a shorter or longer retirement, a different market environment, or a different risk tolerance can all justify a meaningfully different withdrawal rate.
Why the "real" answer depends on your assumptions
The 4% shortcut above gives one number for one specific goal (indefinite sustainability). But most people's actual situation is different — a fixed retirement horizon (say, 25 or 30 years) rather than "forever," and a specific assumed return rather than a generic historical benchmark. Change either input and the required corpus changes meaningfully.
| Scenario | What changes | Effect on corpus needed |
|---|---|---|
| Fixed duration instead of indefinite | You're willing to deplete the corpus to zero over, say, 25-30 years rather than sustain it forever | Generally reduces the corpus needed compared to the 4% indefinite-sustainability estimate |
| Higher assumed return | A more optimistic (or equity-heavy) return assumption | Reduces the corpus needed, but increases risk if returns fall short |
| Step-up withdrawals | Income increases annually to keep pace with rising costs | Increases the corpus needed compared to a flat withdrawal |
| Exit corpus goal above zero | Wanting to leave money behind (inheritance, buffer) | Increases the corpus needed compared to depleting to zero |
This is exactly why a single "you need ₹X" answer online is often misleading — the honest answer is "it depends on your specific assumptions," and the only way to get a number that actually applies to you is to run your own scenario rather than borrow someone else's.
Try the SWP Calculator
Enter ₹50,000 (or your own target), your assumed return, and duration to see exactly how long your corpus lasts — and whether it depletes or grows.
Kavita runs her actual numbers
Instead of stopping at the 4% shortcut, Kavita models two realistic scenarios for her specific situation — a 25-year retirement horizon rather than "forever," and a moderate return assumption rather than the conservative one baked into the 4% rule.
At a withdrawal rate of 6% per year (₹6,00,000 ÷ ₹1,00,00,000) against a moderate assumed annual return, Kavita's corpus is drawing down faster than it's growing — meaning it's on track to deplete before the full 25 years are up, unless her actual returns run higher than assumed.
The same ₹50,000/month against a larger corpus brings the withdrawal rate down to 5% per year — closer to sustainable, though still above the conservative 4% benchmark. Whether this comfortably lasts the full 25 years depends on how her actual returns compare to what she assumed.
Common mistake: picking a corpus size that "feels" big enough without checking the actual withdrawal rate it implies. ₹1 crore sounds substantial, but at ₹50,000/month it's a 6% withdrawal rate — well above the conservative 4% benchmark, and worth stress-testing before relying on it.
Why the corpus number alone isn't the whole answer
Two more factors change what "enough corpus" actually means in practice, beyond the raw arithmetic:
Inflation erodes a flat withdrawal every year
₹50,000 today won't buy the same amount in 15 or 20 years. A corpus that looks sufficient for a flat ₹50,000/month may leave Kavita with meaningfully reduced purchasing power later in retirement, even if the corpus technically "lasts" the full duration on paper. Modelling a step-up withdrawal (increasing the amount annually) or checking the inflation-adjusted real value of the withdrawal gives a more honest picture of what the income will actually cover in future years.
Assumed returns are never guaranteed
Every corpus estimate here rests on an assumed return that may not match actual market performance, especially in the early years of withdrawal — a bad sequence of returns right after retirement starts can deplete a corpus faster than the same average return spread evenly over the whole period would suggest. This is worth treating as a real risk, not just a rounding error, particularly for market-linked corpora rather than fixed-income ones.
Common mistakes when estimating SWP corpus needs
Treating the 4% rule as an exact target rather than a reference point: it's a reasonable starting sanity check, not a guarantee tailored to your specific horizon, market, or risk tolerance.
Ignoring the withdrawal rate the corpus actually implies: a corpus that sounds large in absolute rupee terms can still represent an aggressive, unsustainable withdrawal rate relative to its size — check the percentage, not just the headline number.
Planning around a flat withdrawal with no inflation adjustment: the real purchasing power of a fixed monthly amount declines every year, even though the number on paper stays the same.
Assuming the average return will apply evenly every year: a poor sequence of early returns can deplete a corpus faster than the same long-term average return would suggest if it arrived smoothly.
Frequently asked questions
How much corpus do I need for ₹50,000 a month?
As a rough, conservative estimate using the 4% safe withdrawal rate rule, around ₹1.5 crore would be needed to sustain ₹50,000/month indefinitely. The actual number for your situation depends on your assumed return, how long you need the income to last, and whether you want the corpus to deplete to zero or sustain itself — run your specific numbers to get an accurate answer rather than relying on this shortcut alone.
Is the 4% rule accurate for Indian retirees?
The 4% rule was derived from historical US market data over a 30-year horizon, so it's a useful reference point rather than a rule tailored to Indian markets, inflation, or taxation. It's a reasonable starting sanity check, but modelling your specific assumptions gives a more reliable answer for your situation.
What withdrawal rate is considered safe?
4% per year is the most commonly cited conservative benchmark, based on historical backtesting. A withdrawal rate meaningfully above 4% generally increases the risk of depleting the corpus before a long retirement ends, though the "right" rate for you depends on your specific return assumptions, horizon, and risk tolerance.
Does a bigger corpus always mean a safer withdrawal plan?
Not necessarily on its own — what matters is the withdrawal rate the corpus implies (monthly withdrawal × 12, divided by the corpus). A large corpus with an aggressive withdrawal amount can still represent an unsustainable withdrawal rate, while a smaller corpus with a modest withdrawal can be comfortably sustainable.
Should I plan for a flat withdrawal or one that increases every year?
A flat withdrawal loses real purchasing power every year to inflation, even though the number stays the same on paper. A step-up withdrawal (increasing annually) better preserves purchasing power but requires a larger starting corpus to sustain over the same period — worth modelling both to see the trade-off for your specific numbers.