Key takeaways
- Your employer estimates your full-year tax liability at the start of the financial year, then divides it into monthly TDS deductions
- Since April 2023, the new tax regime is the default for TDS unless you specifically inform your employer you want the old regime
- TDS amounts often aren't equal every month — they adjust as you declare investment proofs, bonuses are paid, or your estimated annual income changes
- If you don't submit investment declarations/proofs on time, your employer will deduct TDS as if you have no deductions at all, even under the old regime
- Excess TDS deducted during the year is refunded only after you file your income tax return
Quick answer
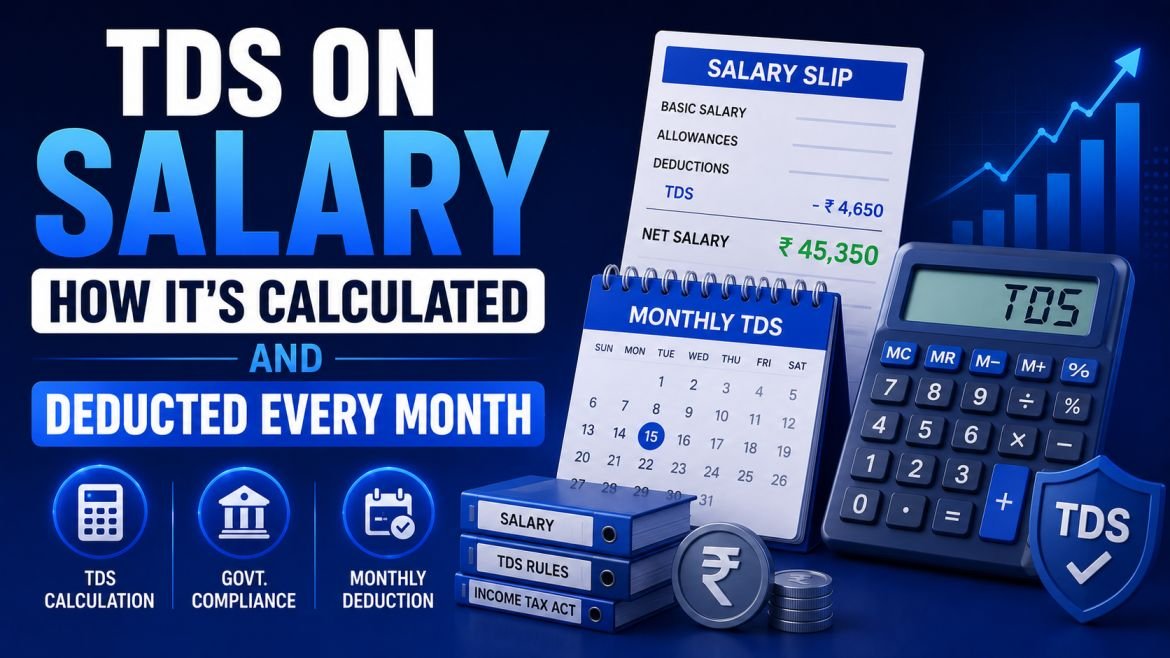
Your employer calculates TDS by estimating your total annual tax liability at the start of the year, then dividing it roughly equally across the remaining months of the financial year. This estimate is based on your salary structure, the tax regime assumed (new regime by default, unless you opt for the old one), and any investment declarations you've submitted. It gets recalculated and adjusted through the year as more accurate information becomes available.
How employers calculate TDS, step by step
| Step | What happens |
|---|---|
| 1 | Employer estimates your total salary for the full financial year, based on your current pay structure |
| 2 | Applicable exemptions are subtracted — standard deduction, and (under old regime, if opted) HRA, LTA, etc. based on declarations |
| 3 | Deductions are subtracted — 80C, 80D, home loan interest, etc. — but only under the old regime, and only if proofs/declarations are submitted |
| 4 | Tax is calculated on the resulting taxable income using the applicable slab rates |
| 5 | The annual tax figure is divided across the remaining months of the financial year and deducted monthly as TDS |
Try the Income Tax Calculator
Use the Income Tax Calculator to estimate your actual annual tax liability and compare against what's being deducted.
Which regime does your employer assume by default?
Since FY 2023-24, the new tax regime is the default for TDS purposes. If you want your employer to calculate TDS based on the old regime instead — to account for HRA, 80C, home loan interest, and other deductions — you need to specifically inform them, usually at the start of the financial year through a declaration form. If you don't, TDS is calculated assuming the new regime, regardless of what regime you might actually prefer to file under.
Good to know: even if your employer deducts TDS under one regime, you're not locked into that regime when you actually file your ITR — salaried individuals with no business income can choose either regime at filing time, with any excess TDS refunded.
Why your monthly TDS amount isn't always the same
Several common events cause your TDS to change mid-year, which is why your take-home pay can fluctuate even without a salary change:
- Investment proof submission: if you declared planned 80C investments in April but haven't submitted proof by a certain deadline, your employer may increase TDS in later months to compensate for the assumed shortfall, then adjust once proofs are submitted.
- Bonus payouts: a bonus is added to that month's income for TDS calculation purposes, often causing a spike in deduction for that specific month.
- Salary revisions: a mid-year raise changes your projected annual income, so your employer recalculates and adjusts remaining TDS accordingly.
- Late declaration changes: switching your declared regime or updating your investment declarations mid-year triggers a recalculation of TDS for the remaining months.
A worked example
Priya's employer estimates her taxable income at ₹11.25 lakh (after ₹75,000 standard deduction), under the new regime.
Tax before rebate: approximately ₹52,500. Since this is under the ₹60,000 Section 87A rebate cap and her taxable income is under ₹12 lakh, her tax liability is fully wiped out to ₹0.
Her employer, having correctly projected this, deducts no TDS through the year — assuming her income and declarations stay consistent with the initial estimate.
If she'd instead opted for the old regime with substantial declared deductions (80C, HRA, home loan interest), her employer would calculate TDS on that lower taxable income instead — but only once she's formally declared her intent to use the old regime and submitted the relevant proofs.
How to legitimately reduce your TDS
- Submit investment declarations early and follow up with proofs before your employer's internal deadline (usually January-February) — missing this often means higher TDS in the last quarter, refundable only after filing.
- Choose the regime that actually suits your income and deduction profile, and inform your employer explicitly rather than letting the default apply.
- Declare all eligible deductions, including HRA, home loan interest (Section 24b), NPS employer contribution, and 80D, if opting for the old regime.
- Update your employer promptly if your income projection changes significantly (e.g., you leave partway through the year), to avoid over- or under-deduction.
Frequently asked questions
Why did my TDS suddenly increase this month?
Common reasons include a bonus payout being added to that month's taxable income, a salary revision changing your projected annual income, or your employer compensating for investment proofs not yet submitted for deductions you'd declared earlier in the year.
Can I choose a different tax regime than what my employer used for TDS?
Yes, for salaried individuals with no business income. You can choose your preferred regime when filing your ITR, regardless of which regime your employer assumed for TDS — any excess tax deducted gets refunded after filing.
What happens if I don't submit investment proofs on time?
Your employer will typically deduct higher TDS in the remaining months, assuming you don't have the deductions you initially declared. You can still claim those deductions when filing your return, and any excess TDS paid will be refunded — but you lose out on the higher take-home pay during the year.
Does TDS get deducted differently if I switch jobs mid-year?
Yes — each employer calculates TDS independently based on the salary they pay you, unless you provide your previous employer's salary and TDS details using Form 12B, which lets your new employer factor in your full-year income for a more accurate calculation. Without this, both employers may apply the basic exemption and slab benefits separately, sometimes resulting in under-deduction that you'd need to settle at filing time.
Is TDS on salary different from TDS on FD interest or other income?
Yes — TDS on salary is calculated based on your estimated annual tax liability at your applicable slab rate, and adjusted monthly. TDS on FD interest, by contrast, is a flat 10% (or 20% without PAN) regardless of your slab, applied only once interest crosses a fixed threshold.
Can my employer deduct TDS even if my total income is below the taxable limit?
They shouldn't, if you've correctly declared your income and any applicable deductions — employers are expected to estimate your actual tax liability, and if that comes to zero, no TDS should be deducted. If TDS is still being deducted despite your income being below the taxable threshold, it's worth checking your declaration with HR/payroll, since it may be a documentation gap rather than a genuine liability.
Form 12BB: how you actually declare deductions to your employer
Form 12BB is the standard declaration form salaried employees submit to claim deductions and exemptions for TDS purposes — it's what turns your "planned" investments into something your employer's payroll system will actually account for.
| What Form 12BB covers | Proof typically required |
|---|---|
| HRA exemption | Rent receipts; landlord's PAN if annual rent exceeds ₹1 lakh |
| Section 80C investments | PPF passbook, ELSS statement, life insurance premium receipt, etc. |
| Home loan interest (Section 24b) | Interest certificate from the lender |
| LTA claim | Travel tickets/proof of travel undertaken |
| Section 80D (health insurance) | Premium payment receipt |
Declaring an investment isn't the same as proving it. Many employees declare planned investments at the start of the year (e.g., "I will invest ₹1.5 lakh in PPF"), but if the actual proof isn't submitted by the employer's internal deadline — typically January or February — the employer reverses the assumed deduction and deducts the shortfall as TDS in the final months of the year, refundable only after filing your return.
Common mistakes with TDS on salary
- Not declaring the old regime explicitly: since the new regime is now the default, employees who actually want the old regime (because of large HRA, home loan interest, or 80C deductions) but forget to declare it end up with higher TDS than necessary, refundable only at filing time.
- Submitting investment proofs late: missing the employer's internal proof-submission deadline is one of the most common reasons for an unexpectedly large TDS deduction in the January-March quarter.
- Not informing the new employer of previous salary via Form 12B: switching jobs without sharing prior salary and TDS details can lead to under-deduction across both employers combined, creating a tax liability discovered only at filing time.
- Assuming TDS equals final tax liability: TDS is an estimate based on declared information — your actual liability is only settled when you file your return, and discrepancies (over or under) are common and normal to reconcile then.